Managing money is not just about earning more or saving regularly. It is also about understanding how money moves, how borrowing affects long-term finances, and how financial decisions support future goals. For people who want to take a more active role in managing their finances, the Infinite Banking Concept is one strategy worth understanding.
The idea has attracted attention among entrepreneurs, business owners, and real estate investors who want greater flexibility in managing their cash flow. However, it is important to understand how the strategy works, what it costs, and why it may not be suitable for everyone before considering it as part of a financial plan.
What Is the Infinite Banking Concept?
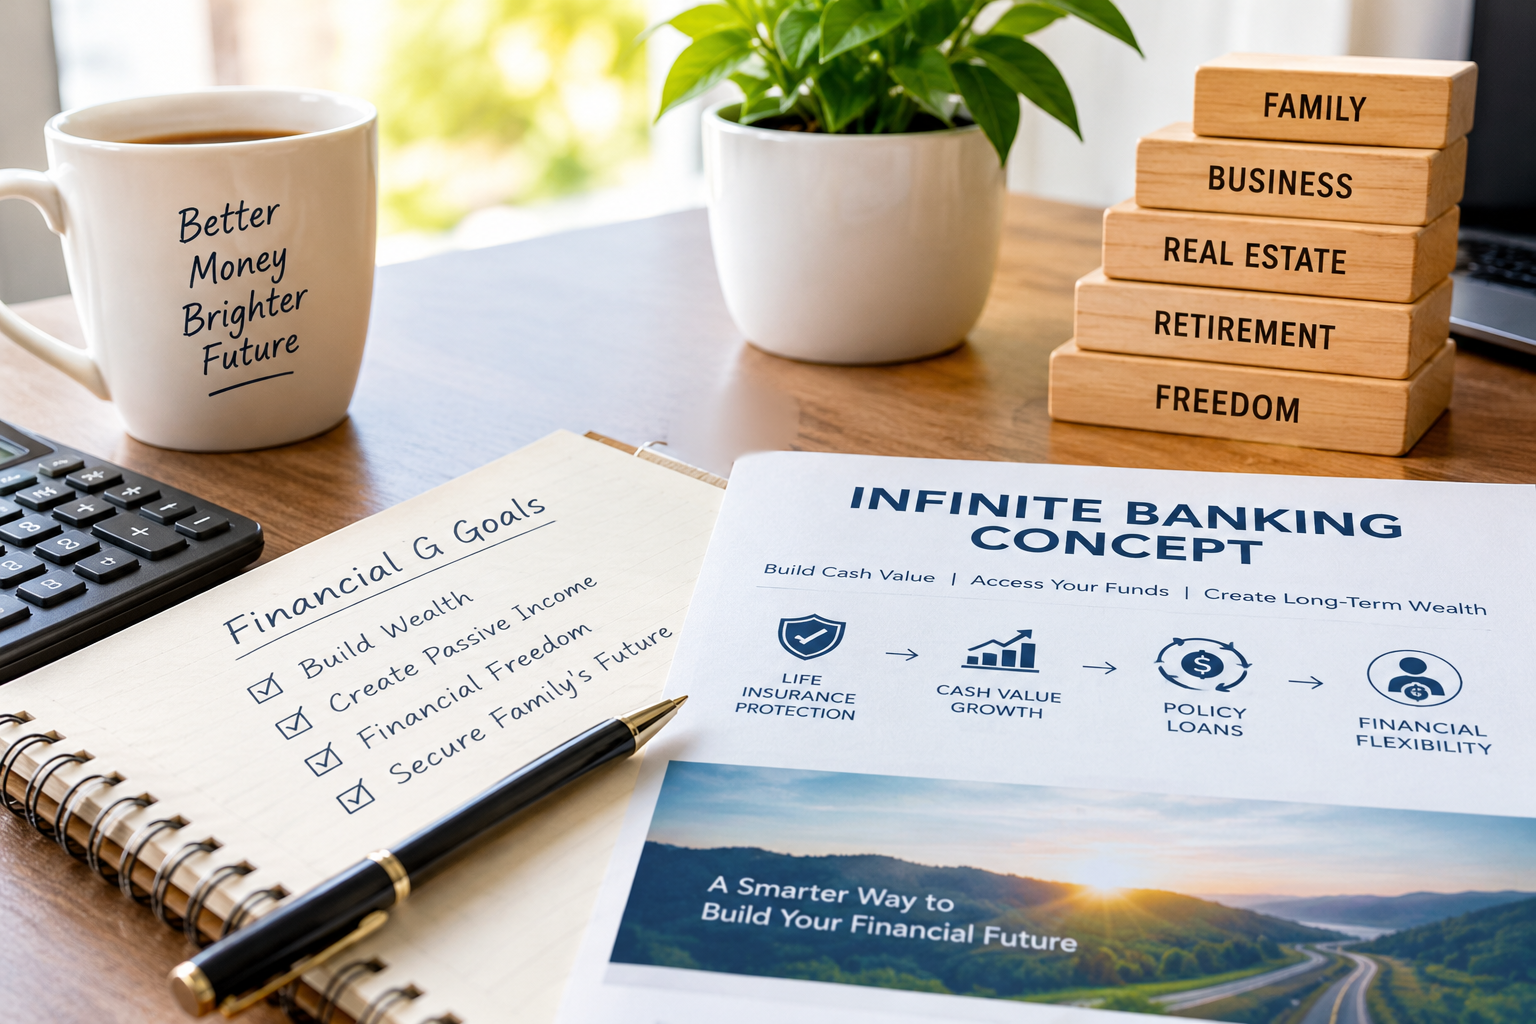
The Infinite Banking Concept (IBC) is a financial strategy that uses the cash value of a specially structured permanent life insurance policy to support personal financing needs. It is commonly associated with dividend-paying whole life insurance policies issued by mutual insurance companies.
The basic idea is to build cash value within the policy over time and then borrow against that value when money is needed. The policyholder can use the loan for eligible purposes, such as business expenses, major purchases, or investment opportunities, subject to the policy terms and the lender’s requirements.
People exploring an infinite banking concept strategy often want to understand how this approach differs from traditional borrowing and whether it can fit into their broader financial goals.
Despite its name, infinite banking does not mean creating unlimited money or eliminating banks completely. Policy loans involve real costs, and the strategy depends on having sufficient cash value, maintaining the policy, and managing repayments responsibly.
How Does Infinite Banking Work?
The process generally begins with purchasing a permanent life insurance policy designed to accumulate cash value. Premiums fund the policy, while insurance costs and other policy charges affect how much value accumulates.
As the policy develops, the owner may be able to borrow against its available cash value. Unlike a conventional bank loan, a policy loan is generally secured by the policy itself. The insurer charges interest, and the borrowed amount is typically deducted when calculating the net benefit payable if the insured dies while the loan remains outstanding.
For example, a business owner might use a policy loan to cover a temporary cash-flow need or purchase equipment. The owner could then repay the loan over time according to a personal repayment plan and the policy’s terms.
However, repayment does not automatically mean that the strategy will outperform other financing options. Policy loan interest, premium commitments, available cash value, and the opportunity cost of using the money all matter when evaluating the overall financial outcome.
Potential Benefits of an Infinite Banking Strategy
One reason people explore infinite banking is the possibility of accessing funds without applying for a conventional loan for every purchase. Depending on the policy and insurer, policyholders may have flexibility in how and when they borrow against available cash value.
Another potential advantage is the combination of cash-value accumulation and life insurance protection. Permanent life insurance may provide a death benefit while building cash value, although the results depend on policy terms, expenses, and how the policy is managed.
For entrepreneurs and real estate investors, access to capital can be particularly important. An available policy loan may provide another financing option when an opportunity arises, especially if conventional lending is slow or restrictive.
Still, these benefits should be considered alongside the costs. Whole life insurance premiums can be substantial, cash value may grow slowly during the early years, and policy loans accrue interest. Dividends, when applicable, are not guaranteed unless specifically stated in the contract.
Important Risks to Understand Before Starting
Infinite banking requires careful planning and a long-term commitment. It may be unsuitable for people who have limited savings, high-interest debt, inconsistent income, or difficulty maintaining regular premium payments.
Policyholders should also understand the consequences of borrowing too much. Outstanding loans can reduce the policy’s net death benefit, and excessive borrowing may put the policy at risk of lapsing. If a policy lapses or is surrendered with outstanding loans, unexpected tax consequences may arise, depending on its cost basis and other circumstances.
Another important consideration is liquidity. Although policy loans can offer flexibility, the cash value available in the early years may be lower than the premiums paid. This means the strategy should not be treated as a substitute for an accessible emergency fund.
Before purchasing a policy, compare its projected values, guaranteed benefits, loan interest rates, fees, and premium requirements with alternative savings and financing options. Independent advice from a qualified financial professional can help clarify the trade-offs.
See also: What a Car Accident Lawyer in Aurora Does and When You Should Contact One
Is Infinite Banking Right for Your Financial Goals?
Deciding whether infinite banking is right for you starts with understanding your financial situation and long-term goals. If you’re exploring this approach, Perry Jeffries offers a useful starting point for learning more about the infinite banking concept and how it may fit into a broader financial plan. Your income, existing savings, borrowing needs, and insurance requirements should all be considered before making a decision.
It is also worth comparing infinite banking with other options, such as high-yield savings accounts and traditional loans. Each approach has different costs, benefits, and limitations, so the right choice depends on your priorities and risk tolerance.